
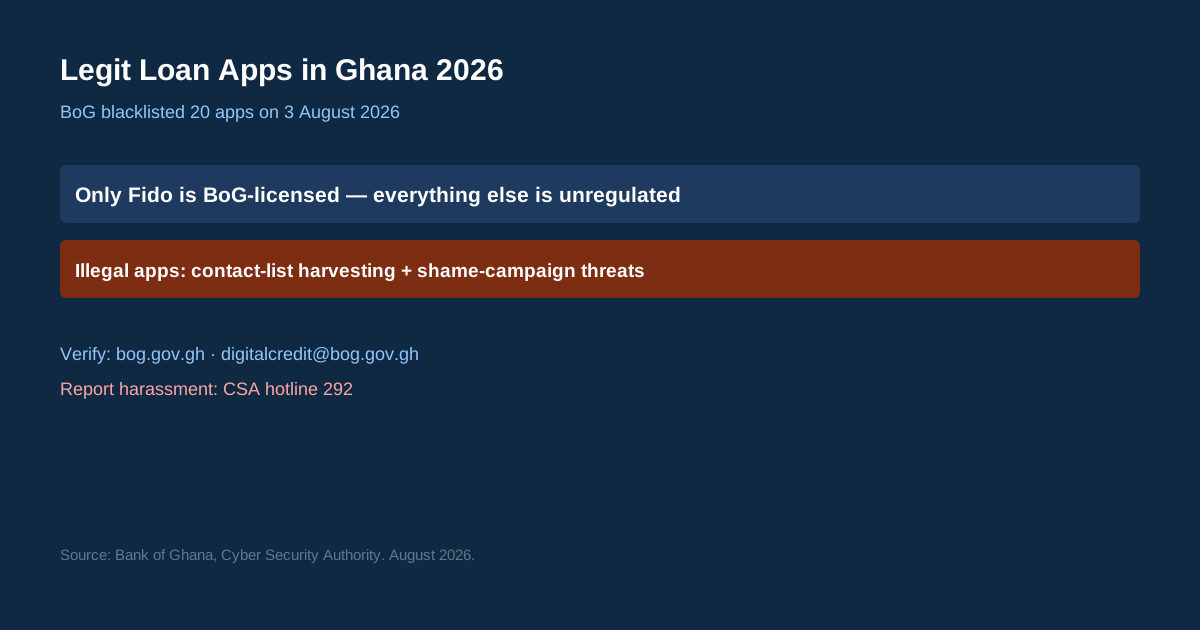
LOANAPPS-GH-20261010A loan app is legal in Ghana only if it is licensed by the Bank of Ghana under the Directive for Digital Credit Service Providers, issued in September 2025 and in force since 1 November 2025; existing apps had until 30 June 2026 to get licensed. On 6 October 2026 the Bank of Ghana named 20 apps operating without a licence, including KudiNow, SikaNow, PocketLoan, Palm Loan and Susu Loan, and told the public to avoid them. Licensed digital loans are capped at GH¢10,000 for terms under a year, must show the full cost before you accept, may not compound interest, and lenders may not contact your phone contacts or shame you publicly. Legal does not mean cheap: MTN QwikLoan charges 6.9% for 30 days and Fido 10–15% per loan.
Licensed digital loans and what they cost
| Product | Lender | Amount | Term | Cost |
|---|---|---|---|---|
| MTN QwikLoan | AFB / Letshego, via MTN MoMo | GH¢25 – 1,000 | 30 days | 6.9% flat for 30 days |
| MTN XtraCash | Forms Capital | up to GH¢5,000 | 7, 28 days or flexible up to 30 | from about 7% to 9% plus 1% fee |
| MTN XpressLoan | Ecobank with Jumo | GH¢50 – 2,000+ | 30 days | about 6.9–8.9% plus 1% fee |
| Fido | Fido Micro Credit (licensed NBFI) | GH¢50 – 500 new; up to GH¢5,000 for repeat borrowers | 7 to 90 days | 10–15% flat per loan, late fee 2% a day up to 20% |
| Bank app loans | Absa (Spark), CBG (ReadyLoan), CalBank, Zenith (Easycash), Fidelity and Republic (Smart Loan) | by account history | short | disclosed in the app |
These rates are per loan, usually for a month, not per year. 6.9% for 30 days is more than 80% a year in simple terms, while Ghana's average bank lending rate was 15.9% in August 2026. A loan app is for a short gap until payday; if you need money for months, a bank or salary loan costs far less. Repay on time: late penalties on mobile money loans can reach 10–12.5% on top, and default is reported to credit bureaus.
Take a typical borrowing: a first-time customer borrows 7,350 shillings worth? No. Let me compute.
Let me recompute: assume you owe GHS 290 and miss the due date by one day. The flat penalty is GHS 22, and the daily penalty is 0.533% of the overdue amount, which is about GHS 1.55. One extra day costs about GHS 23.55 on a GHS 290 loan.
I would pay a small loan early rather than hold the cash one more week. The penalty structure is designed to punish delay, not to reward loyalty. If you cannot pay the full amount on the due date, calling the lender before the date beats hiding from it.
Add a second day and the daily part grows while the flat part stays. On a small balance, the penalty can exceed the original interest for the whole month within a week.
The rules licensed apps must follow
Under the Bank of Ghana directive, a digital credit provider needs a licence, a minimum paid-up capital of GH¢2 million, at least 30% Ghanaian ownership and a physical office for complaints, although loans themselves are processed only digitally. Before you borrow, it must give you a digital pre-agreement with the principal, interest, insurance and every fee; interest is charged for the agreed term and may not be compounded. Harassment, threats, obscene messages, debt shaming on social media and contacting people in your phone book are banned, and your data can be sent to credit bureaus only with your consent. If something goes wrong, complain to the lender first: licensed providers must resolve complaints within 20 days. If they do not, or the app has no licence, report it to the Bank of Ghana; misuse of your personal data can also go to the Data Protection Commission.
How to check an app before you borrow
Look for the lender's name on the Bank of Ghana's list of approved digital credit products and providers, published on its website, and compare it with the company named in the app store and the loan agreement. Treat these as red flags: no company name or licence shown, a request for an upfront «processing» or «insurance» fee before any money arrives, access to your contacts and photos, and a cost that is only revealed after you accept. Google removed more than 200 illegal loan apps from the Play Store in coordination with the central bank, but new ones keep appearing under different names, which is why the October list matters.
Cheaper alternatives
Bank personal and salary loans are priced from the Ghana Reference Rate, 10.04% in October 2026, plus a risk premium, and are far cheaper per year than any loan app; see our guide to bank lending rates in Ghana. Compare bank offers on our personal loans page before using an app for anything longer than a few weeks.
Do these four things the day you take any digital loan:
- write the due date into your phone calendar with a reminder three days before it.
- check the pre-agreement for the exact flat penalty and the daily rate before you accept the money.
- set aside the repayment amount in a separate mobile money wallet as soon as the loan lands.
- if the due date is impossible, contact the lender before it passes and ask for a written extension.