
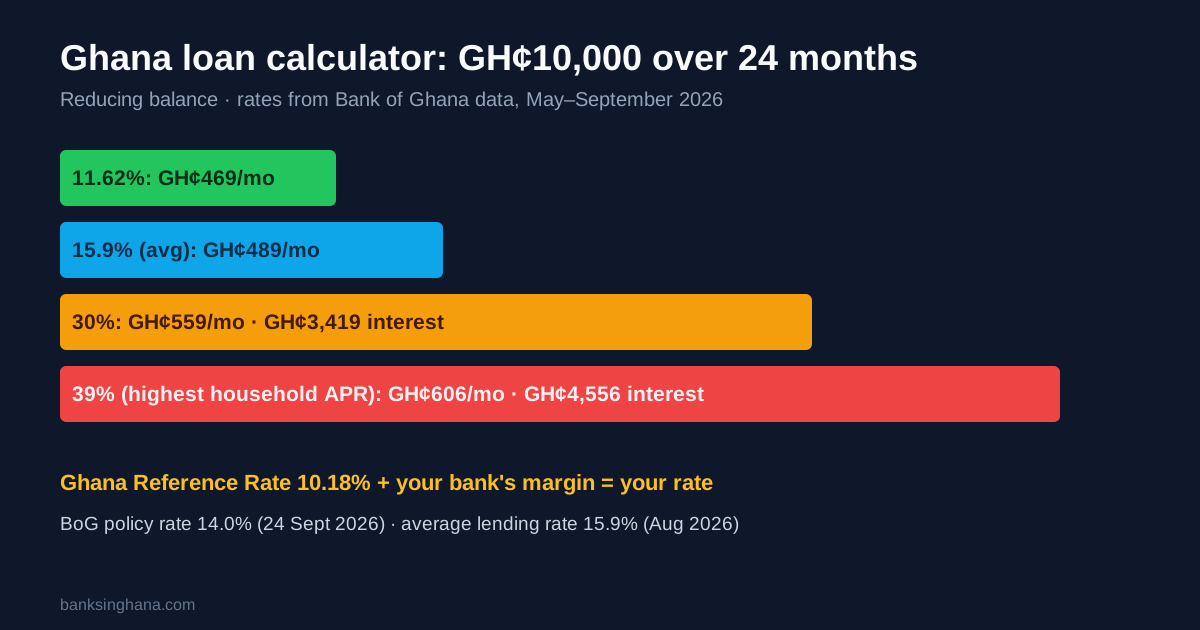
LOANCALC-GH-20260930Enter the amount, term and annual rate below to see your monthly repayment and total cost on the reducing-balance method that Ghanaian banks use. The rate to type in is rarely the Ghana Reference Rate of 10.18% (from 2 September 2026). It is that rate plus the bank's margin. The average bank lending rate was 15.9% in August 2026, and household loan APRs published by the Bank of Ghana for May 2026 ranged from 5.03% to 39%. On GH¢10,000 over two years, that gap is the difference between about GH¢469 and GH¢606 a month.
Ghana loan calculator (reducing balance)
Fees are deducted from the amount paid out, so you receive less than you borrow while repaying the full amount. The effective rate shown includes that effect. Use the APR and fees from the bank's own loan documents for an exact figure.
What GH¢10,000 costs at today's rates
| Annual rate | Where it comes from | 12 months | 24 months | 36 months |
|---|---|---|---|---|
| 11.62% | lowest 1-year household APR, Standard Chartered, May 2026 | GH¢887 / month, GH¢641 interest | GH¢469, GH¢1,255 | GH¢330, GH¢1,892 |
| 15.9% | average bank lending rate, August 2026 | GH¢907, GH¢882 | GH¢489, GH¢1,740 | GH¢351, GH¢2,639 |
| 30% | high-end bank or non-bank quote | GH¢975, GH¢1,698 | GH¢559, GH¢3,419 | GH¢425, GH¢5,283 |
| 39% | highest household APR, May 2026 | GH¢1,020, GH¢2,236 | GH¢606, GH¢4,556 | GH¢475, GH¢7,110 |
Monthly payments are calculated on the reducing balance, and interest is charged only on what you still owe. Two lessons stand out. Extending from 24 to 36 months lowers the payment by about GH¢138 at 15.9% but adds about GH¢900 in interest. At 39% the interest over two years is almost half the amount you borrowed. If a lender quotes a "flat" monthly rate, calculate it on the full original amount for the whole term: a flat rate costs much more than the same number on a reducing balance.
Where the rate you enter comes from
Banks price cedi loans off the Ghana Reference Rate, which the Ghana Association of Banks publishes each month with the Bank of Ghana. It was 15.68% in January 2026, fell to 10.02% by June and has been 10.18% since 2 September. The bank adds a margin for its costs and your risk, and the margin is the part worth negotiating. The Bank of Ghana held its policy rate at 14.0% on 24 September 2026, with the next decision on 18 November, so the reference rate is unlikely to move sharply before then. Rates and benchmarks are tracked on the page comparing bank interest rates in Ghana.
In the Bank of Ghana's May 2026 release, OmniBSIC Bank had the lowest 5-year household APR at 5.03%, Stanbic Bank the lowest 3-year rate at 11.59% and Standard Chartered the lowest 1-year rate at 11.62%. The highest household APRs reached 39%, and the average across all categories was 17.64%. The cheapest rates usually go to salaried customers whose employer has an arrangement with the bank.
Costs the rate does not show
- Processing and facility fees: a percentage of the loan, usually deducted when the money is paid out. Enter them in the calculator: at 3% on GH¢10,000 you receive GH¢9,700 but repay the full GH¢10,000 plus interest.
- Credit life insurance: most bank personal loans require cover for death or permanent disability, charged as a percentage of the loan.
- Salary domiciliation: many banks require your salary to be paid into an account with them for the life of the loan.
- Early repayment: ask in writing whether there is a liquidation charge before you sign.
Banks must disclose an annual percentage rate that includes these charges. Compare APRs, not headline interest rates.
Public sector workers: the Controller affordability limit
For employees paid through the Controller and Accountant-General's Department, loan deductions are capped by the "Controller affordability" figure on the government e-payslip system. Lenders typically keep total deductions to 40–50% of net pay. Under the Public Financial Management Regulations 2019, voluntary deductions need the employee's written agreement and the Controller's approval, and since May 2021 a lender cannot start payroll deductions without a mandate number and PIN that only you can generate. Never give that PIN to anyone except for a loan you have actually agreed to. A loan whose repayment fits within your affordability can still be too expensive, so run the numbers in the calculator above before accepting. For current offers, see the overview of personal loans in Ghana.